Scroll through any listing site and you’ll see the terms mobile home, manufactured home, and modular home used as if they mean the same thing. They don’t. And the difference can change how you finance the home, what it costs to insure, where you’re allowed to put it, and what it’s worth when you sell.
If you’re shopping for an affordable home in 2026, this is one of the most important things to understand before you make an offer.
The Quick Answer
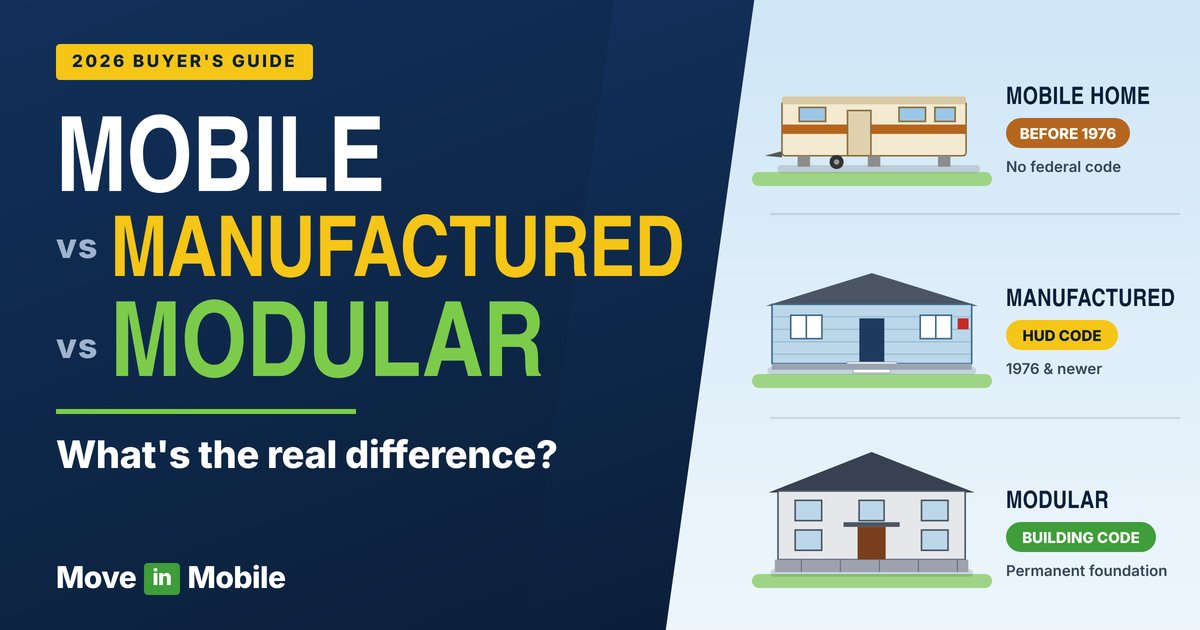
- Mobile home: A factory-built home made before June 15, 1976, before federal construction standards existed.
- Manufactured home: A factory-built home made on or after June 15, 1976, built to the federal HUD Code.
- Modular home: A factory-built home built to the same state and local building codes as a site-built house, then assembled on a permanent foundation.
In everyday conversation, most people (including us) still say “mobile home” for both older and newer homes. But lenders, insurers, and zoning offices care about the exact label. Here’s what each one really means.
What Is a Mobile Home?
Technically, a mobile home is any factory-built home constructed before June 15, 1976. That’s the date the federal Manufactured Home Construction and Safety Standards (the HUD Code) took effect.
Before that date, there was no national standard for how these homes were built. Quality varied widely from one manufacturer to the next. Some older homes are still solid today, but buyers should know a few realities:
- Financing is very limited. Most mainstream lenders and government-backed programs won’t finance a pre-1976 home.
- Insurance can be harder to find and is often more expensive.
- Some parks and towns won’t accept them. Many communities set age limits for homes moving in.
- Resale value is usually lower, because the next buyer faces the same financing hurdles.
That doesn’t mean a pre-1976 home is a bad buy. If the price is right, you’re paying cash, and the home has been well maintained, it can still be a budget-friendly option. Just go in with your eyes open.
What Is a Manufactured Home?
A manufactured home is a factory-built home constructed on or after June 15, 1976, to the federal HUD Code. Today, this is what nearly every new “mobile home” on the market actually is.
The HUD Code sets national standards for:
- Structural strength and design
- Fire safety
- Plumbing, electrical, heating, and cooling systems
- Energy efficiency
- Wind resistance, based on the wind zone where the home will be placed
Because one federal standard applies everywhere, a manufactured home built in one state can be sold and set up in another without being rebuilt to a new code.
Manufactured homes are built in sections, transported to the site, and installed on a foundation system. Depending on how they’re set up, they can be titled as personal property (like a vehicle) or converted to real property (like a house) when permanently attached to land the owner holds.
What Is a Modular Home?
A modular home is also built in a factory, but it follows the same state and local building codes as a traditional site-built house, not the HUD Code.
Modules are trucked to the site, lifted by crane onto a permanent foundation (often a basement or crawl space), and joined together by a local builder. Once finished, a modular home is legally treated like any other house:
- It’s sold with the land as real property
- It’s financed with a traditional mortgage
- It’s taxed and insured like a site-built home
- It tends to appreciate like the homes around it
The tradeoff is cost. Modular homes generally cost more than manufactured homes, require land you own, and involve more site work, permits, and inspections.
Mobile vs Manufactured vs Modular: Side-by-Side Comparison
| Mobile Home | Manufactured Home | Modular Home | |
|---|---|---|---|
| Built | Before June 15, 1976 | On or after June 15, 1976 | Any year |
| Building standard | No federal standard | Federal HUD Code | State and local building codes |
| Foundation | Piers, blocks, or chassis | Piers, blocks, or permanent foundation | Permanent foundation |
| Typical title | Personal property | Personal or real property | Real property |
| Financing | Very limited, often cash only | Chattel loans, FHA, VA, USDA, some conventional | Conventional mortgages |
| Can be placed in a park | Sometimes (age limits common) | Yes | Rarely |
| Relative cost | Lowest | Low to moderate | Highest of the three |
| Resale value | Usually lowest | Varies by condition, location, and land | Similar to nearby site-built homes |
What Changed in 2026: The Chassis Rule
For 50 years, one detail defined a manufactured home: it had to be built on a permanent steel chassis. That frame stays under the home for life, even after it’s set on a foundation.
In 2026, that changed. Congress passed the ROAD to Housing Act, which makes the permanent chassis optional for new manufactured homes. Separately, HUD proposed a rule in June 2026 to let upper-floor sections of multi-story manufactured homes be built without a chassis.
What this means for buyers right now:
- Homes on the market today still have a chassis. HUD has to publish updated construction standards before chassis-free models can ship.
- Safety standards are not changing. Wind, fire, structural, and energy rules in the HUD Code stay in place.
- Over time, the line between manufactured and modular may blur. Chassis-free homes could look and sit more like site-built houses, which may help with zoning, financing, and resale.
If you’re buying in the next year, this won’t change your decision much. But it’s a strong sign that manufactured housing is gaining respect as a mainstream path to homeownership.
Why the Label Matters When You Buy
The type of home you’re looking at affects four big parts of your purchase.
1. Financing
Lenders care more about the build date and title than the floor plan. Pre-1976 mobile homes are often cash-only. Manufactured homes open the door to chattel loans and government-backed options like FHA, VA, and USDA, especially when the home sits on land you own. Modular homes qualify for standard mortgages. If you’re still sorting out your loan options, start with our guide on what credit score you need to buy a mobile home.
2. Insurance
Most insurers write specialized policies for manufactured homes and may limit coverage on older mobile homes. Modular homes are usually covered by a standard homeowners policy. Our breakdown of what insurance you need for a mobile home covers the details.
3. Where You Can Put It
Zoning rules often treat these three types differently. Some towns allow modular homes anywhere a house can go but restrict manufactured homes to certain zones or parks. Many parks won’t accept homes past a certain age. Before buying land, read can you put a mobile home on your own land.
4. Long-Term Value
Homes titled as real property and set on land tend to hold value better than homes on rented lots. That’s one reason some mobile homes can appreciate in value while others lose it.
How to Tell Which Type of Home You’re Looking At
Listings aren’t always accurate, so check the home itself. Here’s what to look for:
- The HUD certification label. Manufactured homes built since 1976 have a small red metal plate on the outside of each section, usually near the tail end. No label is a red flag worth asking about.
- The data plate. Inside the home, usually in a kitchen cabinet, bedroom closet, or near the electrical panel, you’ll find a paper data plate listing the manufacturer, serial number, build date, and wind zone.
- The title or deed. A title (like a vehicle title) usually means personal property. A deed means the home has been converted to, or was built as, real property.
- A state code sticker. Modular homes typically carry a state approval label instead of a HUD label.
- Look underneath. A steel frame under the home with mounting points for axles points to a manufactured or mobile home.
If the HUD label or data plate is missing, ask the seller for documentation before you go further. Replacement verification letters can often be ordered, but it takes time and can delay financing. For more on what to check during a showing, see our mobile home walkthrough guide.
Frequently Asked Questions
Is a manufactured home the same as a mobile home?
Not technically. A mobile home was built before June 15, 1976. A manufactured home was built after that date to the federal HUD Code. In casual conversation, the terms are used interchangeably.
Is a modular home better than a manufactured home?
Neither is “better” for everyone. Modular homes usually hold value like site-built houses and are easier to finance, but they cost more and require land. Manufactured homes cost less and can go in a park or on private land.
Can a manufactured home become real property?
In many states, yes. When a manufactured home is permanently attached to land owned by the same person, the title can often be retired and the home recorded as real property. Rules vary by state, so check with your county.
Can you get a mortgage on a pre-1976 mobile home?
It’s difficult. Most mainstream lenders and government programs require a HUD Code home. Many buyers of older mobile homes pay cash, use seller financing, or take out a personal loan.
Do new manufactured homes still have a chassis?
Yes, for now. A 2026 federal law makes the chassis optional, but HUD still needs to update its standards before chassis-free homes reach the market.
The Bottom Line
Mobile, manufactured, and modular homes all start in a factory, but they live very different lives once they leave it. The build date and building code decide how you finance the home, how you insure it, where it can go, and how it holds value.
Before you fall in love with a listing, confirm exactly what type of home it is. Check the HUD label, find the data plate, and ask how it’s titled. Five minutes of checking can save you weeks of financing headaches.
Ready to start shopping? Browse mobile and manufactured homes for sale on MoveInMobile.com and connect directly with sellers near you.